Understanding the New York food tax is essential for consumers and businesses, as the state has specific rules on which food items are taxable and which are exempt. While most groceries remain tax-free, prepared meals, beverages, and certain snacks may be subject to state and local sales tax. This guide will break down New York's food tax laws, helping you navigate exemptions, taxable items, and compliance requirements.
Is Food Taxable In New York?
In New York, whether food is taxable depends on how it is sold, where it is sold, and whether it qualifies for an exemption. While most unprepared grocery items are tax-exempt, prepared foods, restaurant meals, and certain beverages are subject to New York sales tax. The rates vary depending on local tax laws, as some counties and cities impose their own additional taxes.
Heated and Prepared Foods
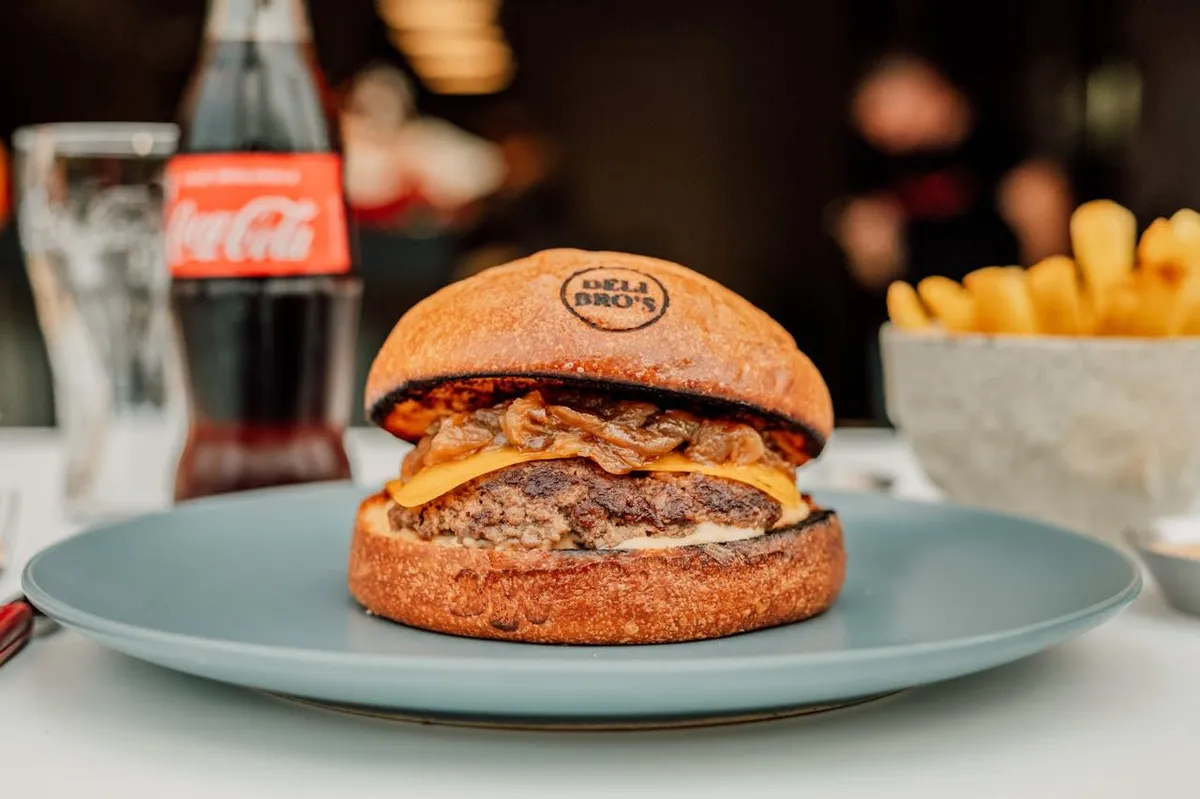
In New York, heated and prepared foods are subject to sales tax, regardless of where they are sold. This includes hot meals from restaurants, delis, supermarkets, and convenience stores, as well as items that are cooked, heated, or assembled for immediate consumption.
Even if a grocery store sells typically tax-exempt items like rotisserie chicken or hot soup, they become taxable when sold in a heated state. Additionally, pre-packaged meals that require minimal preparation, such as sandwiches, salads, and hot buffet items, are also subject to sales tax under New York's food tax laws.
Cold Foods
In New York, cold foods are generally tax-exempt when sold as groceries for home consumption, such as packaged salads, yogurt, and deli meats. However, if cold food is sold as a ready-to-eat meal (like a pre-made salad from a salad bar or a sandwich from a deli counter), it becomes taxable.
Additionally, if a cold food item is sold with a hot beverage or as part of a combination meal, the entire purchase may be subject to sales tax. Businesses must carefully distinguish between grocery items and prepared foods to ensure proper tax collection under New York sales tax rules.
What's Taxable: A 2026 Update
The following categories of food are typically subject to sales tax:
Restaurant meals and prepared foods (including hot or ready-to-eat food from delis, supermarkets, and convenience stores)
Soft drinks, sodas, and fruit-flavored beverages with less than 70% real juice
Bottled water, including flavored and vitamin waters
Candy and confectionery items
Alcoholic beverages, including beer, wine, and spirits
Restaurants, fast food chains, and cafes must charge sales tax on all prepared meals, including takeout, dine-in, and delivery orders.
Self-service salad bars and hot buffets are taxable.
Catered food services are always subject to tax.
New York Food Tax Exemptions and Special Cases
While most groceries in New York are exempt from sales tax, there are special cases and exemptions that businesses and consumers should be aware of. Certain food items may qualify for tax exemptions when purchased for resale, meaning wholesalers and retailers can avoid paying sales tax upfront but must collect it when selling to consumers.
Additionally, while New York does not currently have sales tax holidays for food, other exemptions apply, such as food purchased with SNAP benefits (food stamps), which is always tax-free.
Here's a list of foods that are tax-exempt in New York:
Fresh produce, meat, poultry, and dairy products
Unprepared packaged foods (e.g., canned goods, bread, cereal)
Baby food and formula
Food purchased with food stamps (SNAP benefits)
Businesses that meet economic nexus thresholds must collect and remit sales tax on taxable food sales, even if they operate from out-of-state, ensuring compliance with New York's tax laws.
FAQs
Are groceries taxable in New York? Most groceries in New York are tax-exempt, including fresh produce, dairy, bread, and packaged foods meant for home consumption. However, some items like candy, soda, and prepared foods are taxable under New York sales tax laws.
Are meals taxable in New York? Yes, meals purchased at restaurants, cafes, and food service establishments are subject to sales tax in New York. This includes dine-in, takeout, and delivery orders, as well as prepared foods from grocery store delis and buffets.
Are beverages taxable in New York? Some beverages are taxable, such as soda, soft drinks, fruit-flavored drinks (with less than 70% juice), bottled water, and alcoholic beverages. However, unheated coffee, tea, and milk are generally exempt from sales tax when sold for home consumption.
Overview of Recent Legislation
As of September 2026, the following bills in the New York legislature could affect sales tax on food, beverages, and related categories if enacted. All three remain in committee — none have been signed into law.
Surcharge on Online Delivery Sales
Assembly Bill A5723 proposes a 25-cent surcharge on online deliveries terminating in New York City, with proceeds dedicated to a city infrastructure capital fund. Important for food sellers: the current amended version (A5723A) defines an online delivery sale as any online purchase of tangible personal property delivered to a buyer, with no exemption for food, so online grocery orders delivered in New York City would be covered if the bill passed as written. The bill was introduced February 2025, amended in March 2025, and re-referred to the Assembly Committee on Ways and Means in January 2026.
Increase in Vending Machine Exemption Threshold
Senate Bill S5453 would amend the tax law to raise the exemption threshold for food and drink sold through vending machines. It proposes lifting the current $1.50 exemption (for cash purchases) to $3.00, and the current $2.00 exemption (for any form of payment) to $3.50. The bill is in the Senate Committee on Budget and Revenue.
Sales Tax Reduction for Small Businesses
Senate Bill S1115 proposes lowering the state sales tax rate from 4% to 2% on goods and services purchased from qualifying small businesses — defined as employing 20 or fewer people, being New York–resident, independently owned and operated, and not dominant in their field. The bill is in the Senate Committee on Budget and Revenue.
These proposals reflect ongoing efforts to adapt New York's tax policies to changes in commerce and consumer behavior. We'll update this post if any of the three advance out of committee.
Frequent tax legislation changes — new sales tax surcharges, exemptions, and rate adjustments — make it difficult for businesses to stay compliant, especially when selling across multiple jurisdictions. Kintsugi simplifies sales tax management by automatically updating tax rates, tracking nexus exposure, and ensuring accurate filing so businesses can focus on growth without worrying about tax compliance.
Related resource: For current rates, nexus thresholds, filing deadlines, and FAQs, see Kintsugi's New York Sales Tax Guide.